You earn a solid salary, drive a decent car, and live in a comfortable home. So why does your bank account feel stretched by the end of every month?
The answer often traces back to one number most people have never worked out properly: their net worth. Income and wealth are not the same thing, and confusing them keeps millions of hardworking adults earning more while building less.
This guide shows you how to calculate net worth with a simple formula, the mistakes that quietly distort your result, and the latest 2026 benchmarks so you can see where you truly stand. By the end, you will have an honest snapshot of your finances and a clear plan to improve it.
2026 update: The Federal Reserve’s quarterly Financial Accounts report (released September 11, 2026) shows total U.S. household and nonprofit net worth hit a record of roughly $195.9 trillion in Q2 2026, a jump of $12.8 trillion driven mostly by stock market gains. Records at the national level do not automatically mean your own number is growing, which is exactly why knowing how to calculate net worth for your own household matters.
What Is Net Worth and Why Does It Matter?
Net worth is the most honest number in your financial life. It strips away lifestyle illusions and shows how much wealth you hold after every debt is accounted for.
Think of it as a financial scorecard. Your salary shows what you earn this year. Your net worth shows what you have actually kept from every year before it.
The Net Worth Formula in One Line
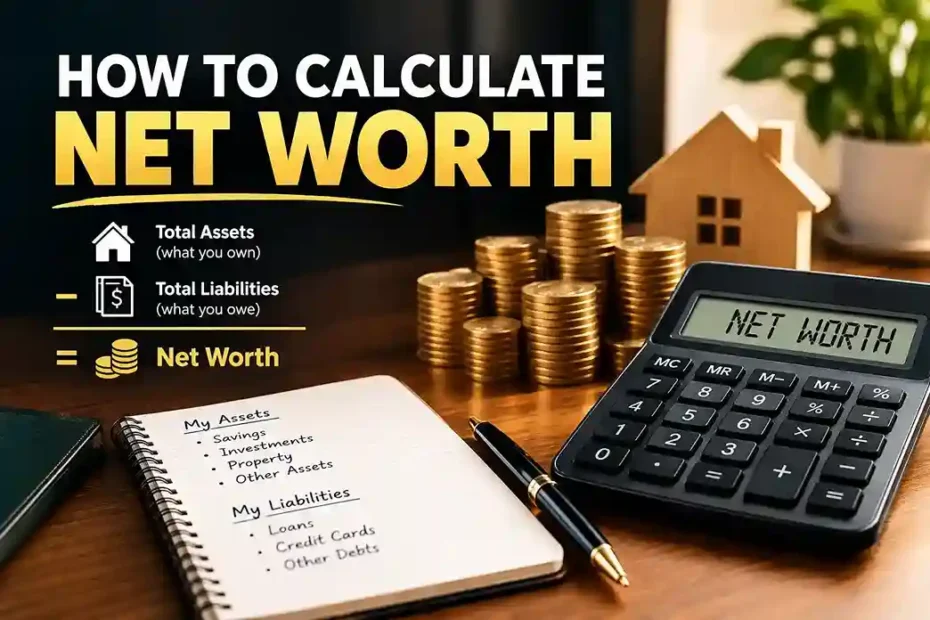
At its core, net worth is a subtraction problem:
Assets − Liabilities = Net Worth
You add up everything you own, subtract everything you owe, and the result is your net worth. No finance degree required. If the result is positive, you own more than you owe. If it is negative, your debts exceed your assets, which is common and fixable, especially for people early in their careers.
Why Income Tells You Almost Nothing About Wealth
A person earning $250,000 a year can have a lower net worth than someone earning $60,000. High earners often upgrade their lifestyles faster than their savings grow, with bigger homes, leased vehicles, and rising credit card balances.
Your income is a river. Your net worth is the lake. A powerful river means little if the lake has a hole in the bottom.
How to Calculate Net Worth in 3 Simple Steps
Grab a notebook, open a spreadsheet, or pull up your banking app. The first time you do this, expect it to take 30 to 45 minutes. After that, quarterly updates take about ten minutes.
Step 1: List Every Asset You Own
Start with everything that holds real monetary value:
- Checking, savings, and money market accounts
- Brokerage accounts and individual stocks
- Retirement accounts (401(k), 403(b), IRA, Roth IRA)
- Real estate, including your primary home
- Vehicles
- Business ownership stakes
- Cryptocurrency and other digital assets
- Valuable items you could realistically sell, such as jewelry or art with a recent appraisal
Record each asset at its current market value, not the price you paid. Your home may be worth more than when you bought it, while your car is almost certainly worth less.
Step 2: Add Up Every Liability
This is the step people rush because it feels uncomfortable. List every mortgage balance, student loan, auto loan, credit card balance, personal loan, medical bill, and any money owed to friends or family.
Pull your latest statements instead of guessing. A rough estimate of your student loan balance produces a number that feels better but tells you nothing useful.
Step 3: Subtract and Read the Result
Total your assets. Total your liabilities. Subtract the second from the first. The figure you get is your net worth.
If the number is lower than you hoped, you are not alone. Treat it as a starting line, not a verdict. The comparison that matters most is your number today versus your number six months from now.
Net Worth Calculation Example
Seeing the math makes it concrete. Here is a sample household:
| Category | Item | Value |
| Assets | Checking and savings | $18,000 |
| 401(k) and IRA | $142,000 | |
| Brokerage account | $25,000 | |
| Home (market value) | $420,000 | |
| Vehicle | $16,000 | |
| Total assets | $621,000 | |
| Liabilities | Mortgage balance | $310,000 |
| Student loans | $24,000 | |
| Auto loan | $9,000 | |
| Credit cards | $4,000 | |
| Total liabilities | $347,000 | |
| Net worth | $621,000 − $347,000 | $274,000 |
Notice how much of the total sits in the home and retirement accounts. That is typical, and it leads to the next question: which assets are truly flexible?
How to Calculate Net Worth: Breaking Down Your Assets
Not all assets are equal. Some convert to cash within hours, while others can take months to sell at a fair price.
Liquid vs. Illiquid Assets
Liquid assets include cash, savings, money market funds, and publicly traded stocks. You can reach them quickly without losing much value.
Illiquid assets include your home, rental properties, private business equity, and collectibles. They hold value, but selling quickly can mean accepting a discount. A healthy profile balances both, because wealth locked entirely in real estate leaves you exposed when an emergency demands fast cash.
How to Value Your Home Accurately
Your home is probably your largest asset, so this number matters. Avoid relying on your property tax assessment, which often lags the market.
Check recent comparable sales in your neighborhood using Zillow, Redfin, or a local agent’s market analysis, and average three to five similar homes sold in the last six months. Online estimates can be off by several percent, so treat them as a range. For precision, a professional appraisal costs a few hundred dollars and gives you a figure you can trust.
Retirement Accounts and Investments
Log into every 401(k), IRA, Roth IRA, and brokerage account and record the current balance, not your total contributions. Many people forget old 401(k) accounts from previous employers. You can search for them through the Department of Labor’s tools or by contacting former HR departments.
Markets move daily, so pick one consistent date each quarter and use that day’s balances every time.
Crypto, Side Businesses, and Other Modern Assets
If you hold cryptocurrency, record it at the market price on your chosen date, and remember that prices can swing sharply between updates. If you own a side business or freelance practice, include it only if you could realistically sell it or its assets. Otherwise, count only the business cash and equipment you could actually liquidate.
How to Calculate Net Worth: Understanding Your Liabilities
Debt is not automatically bad, but unmanaged debt is the fastest way to erode net worth. Sorting liabilities by type shows which ones deserve aggressive payoff.
Short-Term vs. Long-Term Debt
Short-term liabilities include credit card balances, medical bills, and personal loans due within a year. They should be your initial objectives because they typically have the greatest interest rates.
Long-term liabilities include mortgages, student loans, and auto loans. They tend to have lower rates and fixed repayment schedules. A credit card charging 24% APR is an emergency. A mortgage at a modest rate is a manageable expense.
Hidden Liabilities Most People Forget
- Buy now, pay later plans: Services like Afterpay and Klarna create small balances that add up. Five or six active plans can quietly drain hundreds of dollars.
- Unpaid taxes: If you owe the IRS or your state, that debt belongs on your balance sheet even if no notice has arrived.
- Co-signed loans: If you co-signed a loan for a child or relative, the balance is a potential obligation until it is paid off.
- Deferred or resumed student loan payments: Make sure your balance includes accrued interest, not just the original principal.
How to Calculate Net Worth: Benchmarks by Age
Comparing yourself to others is not always productive, but benchmarks show roughly whether you are on track. The most recent complete dataset is the Federal Reserve’s 2022 Survey of Consumer Finances (SCF), published in 2023.
| Age Group | Median Net Worth | Average Net Worth |
| Under 35 | $39,000 | $183,500 |
| 35–44 | $135,600 | $549,600 |
| 45–54 | $247,200 | $975,800 |
| 55–64 | $364,500 | $1,566,900 |
| 65–74 | $409,900 | $1,794,600 |
| 75+ | $335,600 | $1,624,100 |
Source: Federal Reserve, 2022 Survey of Consumer Finances. Overall median household net worth was $192,900, with a mean near $1.06 million.
The true narrative is revealed by the difference between the median and average. A small group of very wealthy households pulls the averages up, so the median is the more realistic comparison point.
What’s New: The 2025 Survey of Consumer Finances
The Fed runs the SCF only every three years. The 2025 survey went into the field in 2025, and its summary results are expected in late 2026. Because home prices and stock markets have moved a great deal since 2022, expect the new figures to differ from the table above. Check the Federal Reserve’s website for the release, and update your comparisons when it arrives.
A Simple Rule of Thumb for Your Target
Those milestones are actually guidelines for retirement savings, not total net worth, so comparing your overall figure to them can mislead you.
A popular alternative from the book The Millionaire Next Door estimates expected net worth as your age multiplied by your pre-tax annual income, divided by ten. For a 40-year-old earning $90,000, that suggests roughly $360,000. Treat it as a rough yardstick, not a rule.
Common Mistakes When You Calculate Net Worth
A miscalculated net worth is worse than none, because it creates false confidence or needless panic. Avoid these traps.
Overvaluing Personal Belongings
Furniture, electronics, clothing, and appliances have almost no resale value compared to what you paid. Including them inflates your total with money you will never realize. Stick to assets you could realistically sell within 90 days at a fair price.
Ignoring Taxes on Retirement Accounts
Your traditional 401(k) balance is not entirely yours. Withdrawals are taxed as ordinary income, so a $500,000 balance might net far less after federal and state taxes. Some planners suggest discounting pre-tax accounts by 20% to 30% for a more conservative figure. Roth accounts, by contrast, are generally tax-free in retirement when rules are met.
Mixing Up Net Worth With Cash Flow
Net worth is a snapshot of what you own minus what you owe. Cash flow is the money moving in and out each month.If your wealth is invested in illiquid assets, you may have a high net worth and poor cash flow; conversely, if you spend the majority of your income, you may have a low net worth and good cash flow.
Forgetting to Update Regularly
A figure from January can be meaningless by July if you paid off a loan, received a bonus, or watched your portfolio swing 15%. Set a calendar reminder for the first weekend of each quarter. Trends, not single snapshots, reveal where you are headed.
Best Tools to Calculate and Track Net Worth
You do not need expensive software, but the right tool makes consistency easier.
Spreadsheets
For most folks, an Excel template or Google Sheets works nicely. Create two columns for assets and liabilities, add a subtraction formula, and update it every quarter. Spreadsheets keep your data private and cost nothing.
Net Worth Tracking Apps
Apps such as Empower (formerly Personal Capital), Monarch Money, and Copilot connect to your accounts and update your net worth automatically. Many previous users have switched to these alternatives since Intuit shut down Mint in 2024. The trade-off is sharing sensitive financial data with a third party, so review each app’s security practices and fees before connecting accounts.
Financial Advisors
A certified financial planner can help if your situation includes business ownership, complex estate planning, or international assets. Fees vary widely, from hourly rates to flat annual fees, so ask for pricing upfront.
How to Grow Your Net Worth After You Calculate It
Knowing your number is only the beginning. The goal is to make it rise year after year through deliberate habits.
Pay Down Debt Strategically
The debt avalanche strategy saves the most money by starting with the balance with the highest interest rate. The debt snowball method targets the smallest balance first and builds momentum through quick wins. Research from Northwestern University’s Kellogg School of Management found that focusing on closing out individual accounts can help people stay motivated and repay more. Choose the method you will actually stick with.
Automate Saving and Investing
Set automatic transfers from checking to your savings and investment accounts on payday, and treat them like bills that must be paid first. As an illustration, investing $200 a month at an assumed 7% average annual return would grow to roughly $104,000 in 20 years. Returns are never guaranteed, but consistency is the part you control.
Capture Your Employer Match
Review your employer’s 401(k) match every year. Leaving matching dollars unclaimed is one of the costliest and easiest mistakes to fix, and it usually takes less than ten minutes.
Build a Cash Buffer
An emergency fund keeps a surprise bill from landing on a high-interest credit card. Many planners suggest three to six months of essential expenses, held in a high-yield savings account.
Conclusion: Your Net Worth Is a Compass, Not a Judgment
Now you know how to calculate net worth: list your assets at current market value, add up every liability honestly, subtract, and repeat each quarter. The result is not a grade on your worth as a person. It is a compass showing which direction your finances are heading.
Block out 30 minutes this week, pull your real numbers, and write them down. That single act puts you ahead of most adults who go through life guessing. Then track it quarterly, attack high-interest debt, and automate your investing so your future self does not have to rely on willpower.
Your net worth will not change overnight, but every quarter you measure it, you gain clarity that compounds just like your investments.